
DRIVING HISTORY, ONE MILE AT A TIME


De geboorte van de Amerikaanse occasionmarkt
Een auto kopen was in Amerika in de eerste jaren van de automobiel
niet alleen een kwestie van geld hebben. Ook de manier waarop een
auto werd betaald, ingeruild en vervolgens weer verkocht, moest nog
worden uitgevonden. De Amerikaanse automarkt ontwikkelde zich
daardoor in de jaren twintig en dertig niet alleen rond de productie
van steeds goedkopere auto's, maar ook rond een geheel nieuw
handels- en financieringssysteem.
Van gebruikte auto naar handelswaar
In de eerste jaren van de automobiel werden auto's meestal contant
betaald. Dat was niet vreemd: auto's waren dure producten en banken
stonden niet bepaald te springen om particulieren geld te lenen voor
een auto. Bovendien was nog helemaal niet duidelijk wat een gebruikte
auto waard was. Een auto kon na enkele jaren behoorlijk versleten zijn
en voor een koper was het moeilijk om de technische staat te
beoordelen. Dat veranderde snel. De massaproductie maakte auto's
goedkoper en steeds meer Amerikanen wilden een auto bezitten. Tegelijkertijd ontstond er een probleem voor de dealer: iemand die een nieuwe auto kocht, had vaak al een oude auto. Wat moest daarmee gebeuren?
Aanvankelijk was een inruilauto voor de dealer eerder een last dan een voordeel. Maar in de jaren twintig werd de ingeruilde auto steeds belangrijker. Dealers begonnen de waarde van de oude auto van de prijs van de nieuwe af te trekken en de inruil daarmee feitelijk als onderdeel van de aanbetaling te gebruiken.
Volgens de National Automobile Dealers Association (NADA) was dat een belangrijke reden voor de groeiende behoefte aan betrouwbare informatie over gebruikte-autowaarden. Een tweede reden was nog belangrijker: gebruikte auto's werden in de jaren twintig zó talrijk dat ze een zelfstandige markt vormden. NADA stelde vast dat gebruikte auto's vanaf de jaren twintig tot en met de jaren vijftig structureel talrijker waren dan auto's die via franchisedealers nieuw werden verkocht.
Het ontstaan van de Amerikaanse occasiondealer
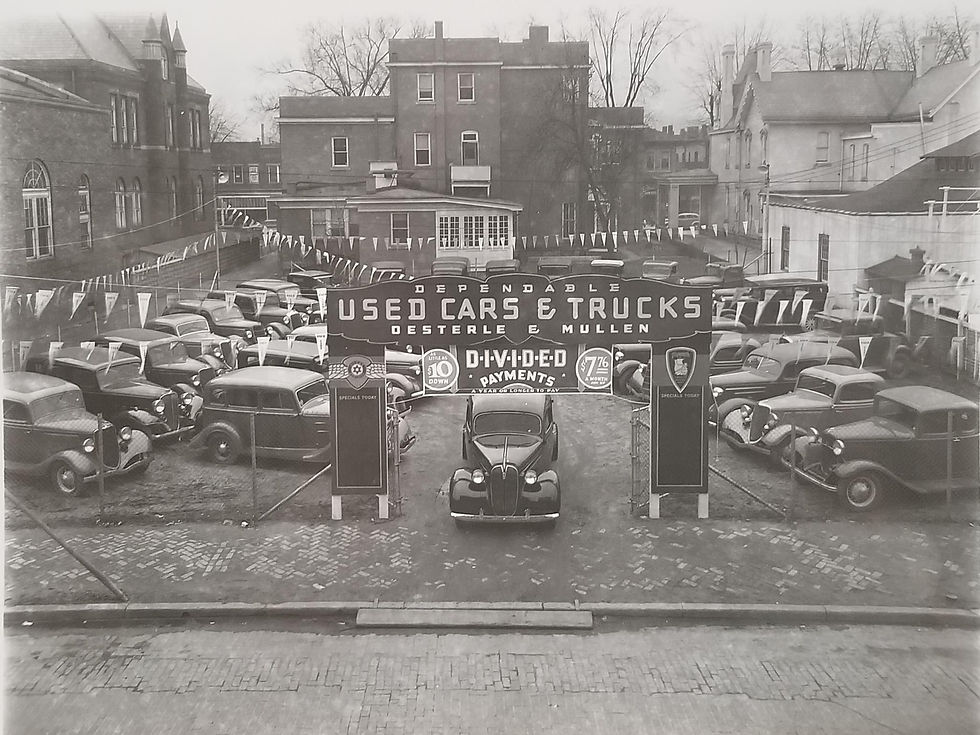
Daarmee ontstond ook het typische Amerikaanse dealerbedrijf zoals we dat tegenwoordig nog kennen. Een dealer verkocht een nieuwe auto, nam de oude auto van de klant in, maakte die eventueel technisch en cosmetisch weer verkoopbaar en zette hem vervolgens opnieuw op zijn terrein.
Dat laatste was niet altijd eenvoudig. In de jaren twintig was de reputatie van gebruikte auto's bepaald niet geweldig. De koper moest maar afwachten wat hij precies kreeg. Een gebruikte auto kon er aan de buitenkant prachtig uitzien, maar mechanisch behoorlijk slecht zijn.
De fabrikanten en hun dealers hadden daarom een probleem: hoe overtuig je iemand ervan dat een gebruikte auto van jouw dealer beter of betrouwbaarder is dan een willekeurige auto die ergens langs de weg of op een onafhankelijk occasionterrein wordt aangeboden?



Chevrolet OK Used Cars
Chevrolet begon in het midden van de jaren twintig met een eigen programma voor gebruikte auto's. Het bekendste onderdeel daarvan was het rode OK-tag. Een advertentie uit 1928 beschreef het als een controlekaart waarop stond welke onderdelen van de auto waren gecontroleerd en welke eventueel waren gereconditioneerd voordat de auto op het verkoopterrein kwam te staan.
Het was dus meer dan alleen een leuk logo. De rode OK-tag moest de koper het gevoel geven dat de auto door de Chevrolet-dealer daadwerkelijk was bekeken en niet zomaar als ingeruilde auto op het terrein was gezet.
De controle omvatte een groot aantal onderdelen, van motor, transmissie en radiator tot carrosserie, lak en interieur. Chevrolet presenteerde de tag als bescherming voor de koper: een auto met zo'n aanduiding had volgens het systeem de noodzakelijke controle en eventuele reconditionering door deskundige monteurs ondergaan.
Een belangrijk detail is dat een Chevrolet-dealer niet uitsluitend Chevrolets verkocht op zijn gebruikte-autoterrein. In advertenties uit die tijd zijn ook gebruikte Fords, Plymouths en andere merken te vinden. Dat was logisch: een klant die een nieuwe Chevrolet kocht, kon immers heel goed een Ford of ander merk als inruilauto achterlaten.
De gebruikte-autoafdeling moest dus niet alleen zorgen voor een nieuwe verkoop, maar ook voor een tweede verkoop. De beroemde rode tag werd aanvankelijk aan de radiator geplaatst. Toen de klassieke, vrijstaande radiateurs uit het straatbeeld verdwenen, verhuisde de aanduiding naar het interieur. Het concept bleef hetzelfde: Chevrolet wilde een gebruikte auto minder onzeker maken voor de koper. In de jaren vijftig en zestig werd OK Used Cars bovendien een zeer herkenbare reclameterm. De gebruikte auto werd niet langer uitsluitend als een goedkope oude auto gepresenteerd, maar als een betrouwbare en betaalbare auto waarmee je nog steeds voor de dag kon komen. Dat was belangrijk in een periode waarin Amerikaanse fabrikanten vrijwel ieder modeljaar nieuwe carrosserieën en styling introduceerden. Een auto van drie jaar oud zag er daardoor al snel zichtbaar ouder uit.


Een meeting van Chevrolet dealers in 1949 met de focus op het OK Used Car label. Foto's van de bibliotheek van de universiteit van Utah.


Ford A-1 Used Cars
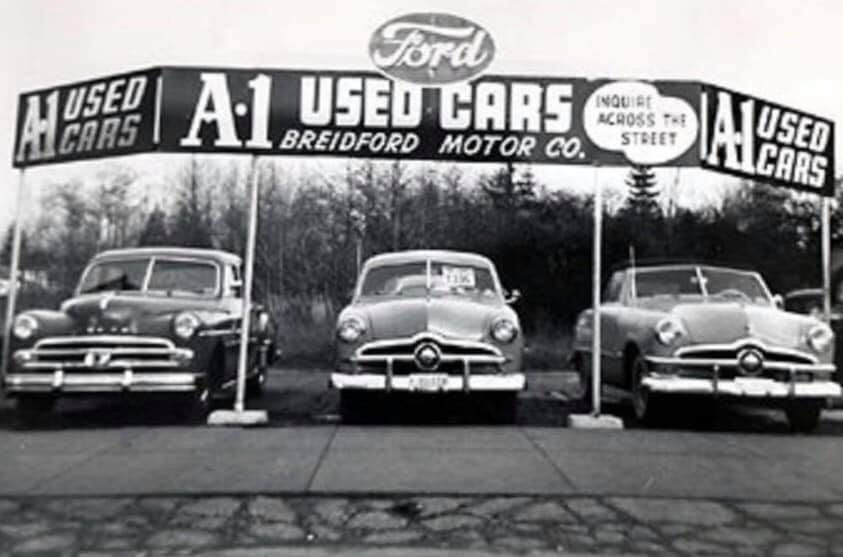
Ford gebruikte een vergelijkbaar idee met A-1 Used Cars and Trucks. In Amerikaanse advertenties uit de jaren vijftig werd de koper rechtstreeks aangesproken met de boodschap dat hij voor een A-1 gebruikte auto naar zijn Ford-dealer moest gaan.
Ook hier ging het niet alleen om Fords. Ford-dealers namen auto's van allerlei merken in. De gebruikte-autotak was immers juist afhankelijk van de auto's die klanten bij de aanschaf van een nieuwe Ford achterlieten.
A-1 moet daarbij niet zonder meer worden voorgesteld als exact hetzelfde systeem als Chevrolet's OK-tag. Bij Chevrolet is het historische bewijs voor een herkenbaar inspectie- en reconditioneringssysteem met de rode tag duidelijk. Bij Ford zien we A-1 vooral terug als een door Ford-dealers gebruikt kwaliteits- en marketingconcept, waarbij inspectie, garantie en de betrouwbaarheid van het Ford-dealernetwerk centraal stonden.
In advertenties werden termen gebruikt als “A-1 Real Values”, “A-1 Better Buys” en “A-1 Used Cars and Trucks”. Sommige dealers gaven bovendien een concrete garantie op A-1-occasions. Daarmee verkocht Ford in feite niet alleen de gebruikte auto, maar ook het vertrouwen dat de koper bij een officiële Ford-dealer kocht.


Maar hoe betaalde je dat allemaal?
Minstens zo belangrijk als de opkomst van de occasionmarkt was de ontwikkeling van autofinanciering.
Daar zat een merkwaardige tegenstelling in. De auto werd dankzij massaproductie steeds goedkoper, maar voor een gemiddeld gezin bleef het nog steeds een grote aankoop. Banken waren aanvankelijk terughoudend met autoleningen. In de jaren tien ontstonden daarom gespecialiseerde sales finance companies: ondernemingen die zich specifiek bezighielden met het financieren van auto's.
Het systeem werkte anders dan een eenvoudige lening van de bank aan de koper. Stel dat een auto $1.000 kostte. De klant betaalde bijvoorbeeld $400 aan de dealer en tekende voor de resterende $600. De financieringsmaatschappij financierde vervolgens de transactie en nam het betalingscontract over. De auto diende daarbij als zekerheid. Bij wanbetaling kon de auto worden teruggenomen.
Er waren bovendien allerlei varianten. In de jaren twintig kon een auto worden aangeschaft met een relatief kleine aanbetaling, gevolgd door wekelijkse of maandelijkse betalingen. Sommige constructies eindigden met een relatief grote laatste betaling, wat tegenwoordig een balloon payment zou worden genoemd.
Het Amerikaanse systeem maakte het daardoor mogelijk om een auto te bezitten zonder het volledige bedrag bij aankoop beschikbaar te hebben. Dat klinkt tegenwoordig normaal, maar was in de jaren twintig een belangrijke verandering.
Niet alleen de klant werd gefinancierd
Nog interessanter is dat de financiering niet alleen voor de consument bedoeld was. Een dealer moest immers eerst auto's inkopen om ze te kunnen verkopen. Ook daarvoor ontstond krediet. Financiële instellingen financierden de voorraad van dealers. De auto's op het dealerterrein waren daarmee in feite onderdeel van een met krediet gefinancierde voorraad. Daarmee ontstond een dubbele financiële keten:
fabriek → financier → dealer → voorraad
en vervolgens:
dealer → financier → klant → maandelijkse betalingen
De dealer kon daardoor een veel grotere voorraad aanhouden dan wanneer hij iedere auto volledig uit eigen middelen had moeten betalen. Dit systeem van voorraadfinanciering zou later bekend worden als floorplan financing en is nog altijd een fundamenteel onderdeel van de Amerikaanse autohandel.
GM begrijpt het systeem vroeg
General Motors zag al vroeg dat financiering niet alleen een dienst aan de klant was, maar ook een manier om de hele verkoopketen te ondersteunen. In 1919 richtte GM de General Motors Acceptance Corporation (GMAC) op. De maatschappij financierde zowel dealers als consumenten en werd daarmee een belangrijk onderdeel van GM's verkooporganisatie. In 1923 financierde GMAC volgens historische gegevens al een groot deel van de nieuwe GM-aankopen. Dat was een belangrijk voordeel. GM hoefde niet uitsluitend afhankelijk te zijn van banken die bereid waren een auto te financieren. Het bedrijf beschikte over een eigen financiële arm die de verkoop van zijn auto's kon ondersteunen. De auto-industrie kreeg daarmee feitelijk een systeem waarin productie, dealerbedrijf en krediet steeds nauwer met elkaar verbonden raakten.
Henry Ford moest eerst niets van krediet hebben
Ford koos aanvankelijk een totaal andere weg. Henry Ford was principieel tegen consumentenkrediet. Hij vond het idee dat iemand geld moest lenen om een auto te kopen ongewenst. Ford verkocht auto's daarom bij voorkeur zonder de financiële constructies die GM steeds succesvoller maakte.
In 1923 kwam Ford met het Ford Weekly Purchase Plan. In plaats van een lening af te sluiten, kon een klant iedere week vijf dollar bij een bank storten totdat hij genoeg had gespaard om een Model T te kopen.
Het idee was eenvoudig: eerst sparen, daarna kopen. Het probleem was alleen dat de klant daarvoor geen speciaal Ford-plan nodig had; hij kon net zo goed zelf sparen.
De concurrentie dwong Ford uiteindelijk alsnog richting consumentenkrediet. Ford-dealers konden vanaf het einde van de jaren twintig financiering aanbieden en uiteindelijk werd krediet net zo goed onderdeel van het Ford-verkoopmodel. Een echte Ford-financieringsmaatschappij zoals we die tegenwoordig kennen, Ford Motor Credit, kwam overigens pas in 1959.
De gebruikte auto maakt financiering nog interessanter
De financieringsrevolutie en de groei van de occasionmarkt versterkten elkaar.
Wie een nieuwe auto kocht, kon zijn oude auto inruilen. De waarde daarvan werd onderdeel van de nieuwe transactie. De dealer had vervolgens een gebruikte auto die opnieuw verkocht kon worden. Die tweede koper hoefde op zijn beurt niet noodzakelijk over het volledige bedrag te beschikken en kon eveneens gebruikmaken van krediet.
Zo kon één auto gedurende zijn leven verschillende keren onderdeel worden van een gefinancierde transactie.
Voor de dealer betekende dit bovendien dat een gebruikte auto niet alleen een probleem was dat hij moest zien kwijt te raken. Het werd een voorraadartikel met een eigen marge.
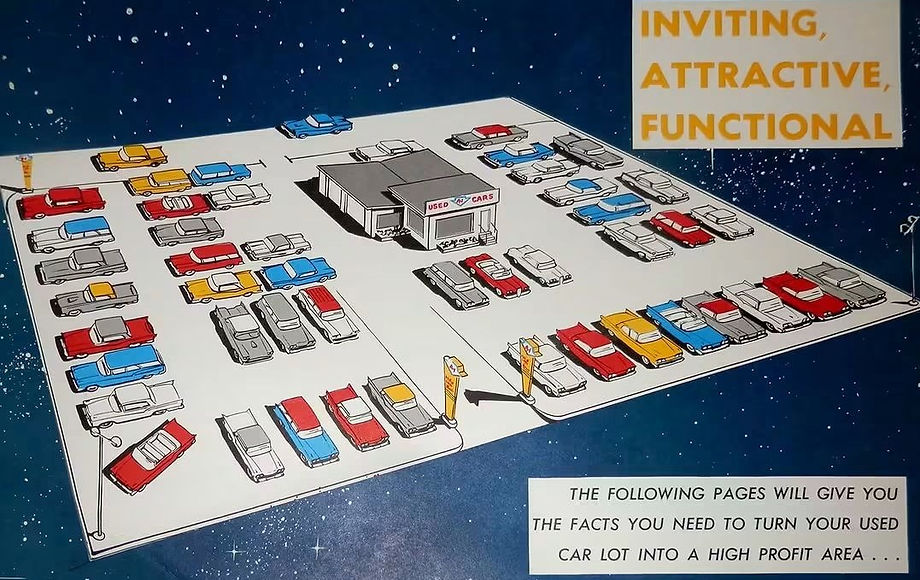
Daarmee ontstond de basis van het Amerikaanse dealerbedrijf zoals dat later zo herkenbaar zou worden: een groot terrein vol nieuwe auto's, een aparte voorraad gebruikte auto's, een werkplaats die ingeruilde auto's kon reconditioneren, een financier die zowel dealer als klant kon bedienen en een verkoper die de verschillende onderdelen van de deal aan elkaar knoopte.
Maar wat was een gebruikte auto waard?
Daarmee kwam het volgende probleem naar voren. Als een dealer een ingeruilde auto moest accepteren, moest hij weten wat die auto waard was.
NADA begon daarom al in 1922 met het verzamelen en bestuderen van gegevens over gebruikte-autowaarden. In 1933 resulteerde dat in de N.A.D.A. Official Used Car Guide, die in zijn eerste jaar voor 21 regio's verscheen en bijna 40.000 exemplaren omvatte. NADA ontwikkelde later ook een standaardformulier voor het taxeren van gebruikte auto's en leidde dealers op in het gebruik van de Guide.
Maar NADA was niet de enige.
In 1926 verscheen de eerste Kelley Blue Book. Les Kelley was zelf actief in de gebruikte-autohandel in Los Angeles. Hij had aanvankelijk een lijst samengesteld van auto's die hij wilde kopen en wat hij ervoor wilde betalen. Andere dealers en banken begonnen die informatie te gebruiken, waarna de lijst uitgroeide tot een officiële prijsgids.
Dat is een mooi voorbeeld van hoe de behoefte vanuit de praktijk ontstond. Een dealer die iedere dag gebruikte auto's inkocht, had behoefte aan een referentiepunt. Een bank die een auto financierde, wilde eveneens weten welke waarde er tegenover de lening stond.
NADA en Kelley Blue Book ontwikkelden zich vervolgens ieder op hun eigen manier tot belangrijke referenties voor de Amerikaanse autohandel. De precieze geschiedenis van Kelley Blue Book verdient een eigen verhaal; voor de ontwikkeling van de occasionmarkt is vooral van belang dat er vanaf de jaren twintig steeds meer sprake was van een gemeenschappelijke taal voor de waarde van een gebruikte auto.
Van gevoel naar systeem
Daarmee werd de occasionhandel steeds professioneler.
Een dealer hoefde niet meer uitsluitend op ervaring en onderhandeling te bepalen wat een ingeruilde auto waard was. Er kwamen waardegidsen, taxatieformulieren, inspecties en reconditioneringsprocedures. Een gebruikte auto kreeg een inkoopwaarde, een bedrag dat nodig was om hem verkoopklaar te maken en uiteindelijk een verkoopprijs waarin de marge van de dealer zat. Dat maakte de occasion tot een zelfstandig handelsproduct. De rode OK-tag van Chevrolet en het A-1-logo van Ford waren de zichtbare kant van die ontwikkeling. Daarachter zat inmiddels een veel groter systeem van taxeren, financieren, inruilen, repareren en opnieuw verkopen.
Een zichzelf versterkend systeem
Vanaf de jaren dertig begonnen al deze ontwikkelingen elkaar te versterken.
De fabriek produceerde grote aantallen nieuwe auto's. De financieringsmaatschappij maakte het mogelijk dat de dealer zijn voorraad kon betalen en dat de consument de auto kon aanschaffen zonder het volledige bedrag direct beschikbaar te hebben. De dealer nam de oude auto in, bepaalde daar een inruilwaarde voor en verkocht die vervolgens opnieuw. NADA en Kelley Blue Book hielpen om die waarde beter te bepalen. Chevrolet gebruikte OK Used Cars om vertrouwen in zijn occasions te creëren en Ford deed iets vergelijkbaars met A-1 Used Cars and Trucks. Het was dus niet één uitvinding die de Amerikaanse occasionmarkt groot maakte. Het was de combinatie van massaproductie, financiering, inruil, waardebepaling, reconditionering en marketing.
En daarmee ontstond een systeem dat voor Amerikanen uiteindelijk volkomen normaal werd: een nieuwe auto

Zelfs een zeldzame Tucker is uiteindelijk een 'used car'.


Kelly Blue book


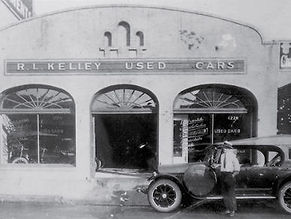
Kelley Blue Book
Les Kelley had no money and no job when he came to California in 1914. He did have an old car in good condition because he was handy and had overhauled the car himself. His friends admired his car and wanted to buy it. After much hassle he sold it to one of them. With that money I bought another old Ford. Traded after an overhaul he bought this car and traded two of them in with a down payment. He also overhauled these and sold them again. In this way he regularly bought and sold cars and used them to pay for his school.
Les, now 21, founds the Kelly Kar Company in 1918 in Los Angeles. He started out with 3 Model T Fords and one employee, his 13-year-old brother Buster, on a piece of land that he leased from another car dealer. His cars were under the self-invented label 'Selected Blue Seal Automobiles'. When Buster was 18 he ran the workshop with 12 mechanics and Les was the sales manager. They did very well and soon had to look for another more spacious location. In the 1920s, Les was dissatisfied with the fact that all the cars he sold were black. Black was the fastest drying color. One day, when Buster spoke to an employee who was about to paint a car, he suggested painting the car pink. Buster thought it was a strange proposition, but the employee said he would repaint the car for free if he didn't sell. Sales skyrocketed, so much so that he soon ran out of stock. lesson so he drew up lists of cars he wanted with prices he was willing to pay for them and circulated them to other dealers and banks. People quickly relied on his insights and the lists and booklets were used by banks and auto companies in the Los Angeles area. Les soon realized that this would allow him to continue to provide good service to the industry and to the banks. Meanwhile, DuPont came up with a paint that, in any color, could dry in two time instead of a month, instantly changing the entire industry.
Using his company's data, he published his first booklet in 1926. The first booklet was published under the name 'Blue Book of Motor Car Values'. At the time, the term 'blue book' was used for address books that listed the people of high social status. (social registers). Emily Post had just published a book on etiquette that would be known as 'The Blue book of social usage'. The term 'blue book' therefore equaled 'valuable information'. Because of the blue and gold ribbon that came with his 'Selected Blue Seal Automobiles', he also chose that logo to display on the cover of his booklet. Les's booklet contained thousands of new prices and cash values.
In the 1930s, there was a daily line of cars in front of the door to be appraised. By now Buster had become the General Manager. When the number subscriptions boomed, the company moved to the corner of Figueroa and Pico in Los Angeles and became the largest used car dealer in the world. The workshop with claims department was at a different location to Pico and more than a hundred people worked there. They only sold used cars that were bought directly from the owners or trade-in dealers. After all, dealers didn't sell used cars. In the years after the stock market crash, entire stocks were sometimes bought from bankrupt dealers. The Kelleys also started their own insurance company and car club. Both were sold with the cars and sometimes even driving lessons had to be given to the buyers,
In the 1940s, the cars were bought in the East and transported to LA by rail cars, sometimes as much as 1,000 a month. Soldiers who had to go to the front could sell their car to the Kelley Kar Company and drive it until they left. After the Second World War, the demand for cars increased enormously and with it the demand and popularity of Kelley's books. The GI Credit plan is now being offered for returning soldiers. You do not have to pay, but you do have to pay off in 5 years. During World War II, the government uses the Blue Book values to set a maximum price for used cars that would otherwise become unaffordable due to high demand and shortages. Les, meanwhile, bought a Ford franchise that allowed the company to sell new cars as well. Advertising innovations consisted of full page newspaper advertisements and for the first time also television commercials in which the cars were described and promoted. The commercials sometimes lasted 15 minutes and showed Buster walking around the showroom and talking about their 30-day warranty. One could exchange a purchased car for another equivalent or more expensive car within 30 days.
In the 1950s Kelley was not only the largest used car dealer but also the largest Ford dealer in the country.
Kelley stopped selling cars in 1962. Partly because they had to move again due to growth. Due to the increased land prices in LA, this was stopped. Since the sale founded Buster together with his son Bob, he devoted himself entirely to the composition of the blue book that is published every other month. Kelley was the first publication to use a vehicle's odometer reading to determine its value. They also develop guides for motorhomes, caravans, ATVs, snowmobiles and motorcycles. In the 1970s, the average age of a car was 9 years. The booklet only lasted until age 7. A new guide was released, the Older Car Guide. Later there was even an Early Model Guide dating back to 1946. In 1978 Bob's son Mike also joins the firm. Mike had an IT background which gave the company an edge in technology. The company was big in providing information and that went through separate lists, into booklets, and after Mike took office, also through software and later the internet. In 1981 Mike becomes General Manager.
After Les Kelley's death in 1990, he was 93 and was still involved in his business, Bob Kelley continued the work, until he and his son Mike called it quits in 2000.
In 1993, a guide was first introduced published for consumers. The book was regularly found on the USA Today best seller list and was the best-selling automotive book. In 1995, the company set up a website where people could look up the prices of new cars. The residual values followed a year later. Within two years this was the most visited website on the internet (conditions for this claim unknown to me). In the first three weeks it asked for $3.95 per report but after complaints they chose to offer the reports for free but supported with advertising. The website was at number 2,144 in June 2017 in a by Alexa Internet compiled list of the most visited websites. Software is also available for dealers, financial institutions and insurance companies.
For many years there was no price information on new cars until Senator Monroney introduced a law in 1958 that required a price tag on every new car showing the equipment, as well as the Manufacturer's Recommended Retail Price (MSRP). After the introduction of this law, consumer confidence increased even more and sales also increased. This Window Sticker is still called the Monroney label today. Used cars, however, were provided with texts on the windscreen with 'low mileage', 'fully loaded', 'air conditioning', etc. on the windscreen until well into the 1990s. Kelley innovated again and introduced software for dealers in 1992 with which one could open a Blue Book window. sticker could print with the mileage, equipment etc along with the Blue Book value and the dealer asking price.
The insurance business and auto club were shut down decades ago, but the company still reports market values for new and used cars and motorcycles. In addition to the market value, a purchase value is also provided. Everything is based on real transactions and is regularly adjusted to market conditions. For new cars, the suggested retail prices and invoice prices are communicated. In 2002 they introduce the 'Fair Purchase Price' that helps consumers make an informed decision when buying a car. It concerns an average transaction price per region, ie the real invoiced price instead of the MSRP suggested retail price. In 2004 CDM Data is bought. Using their software, dealers can list and advertise cars.
For used vehicles communicate the market value, sales value, trade-in value and trade value, they also publish reviews and ratings and a cost overview for the first 5 years of a used car. In the early years of the 21st century, new car previews, comparisons, Blue Book advertisements and a view of the market are introduced. The number of visits to the website exceeds 10 million per month. There will even be awards for the vehicles with the best residual value. The website will be expanded with consumer reviews, residual values, video presentations, 360 degree videos and more. It already attracts 160 million visitors per year.
In 2010, the company was acquired by Autotrader.com (which itself is part of Cox Automotive). In 2013, it entered into a partnership with Bitauto Holdings LTD to be able to operate in China as well.

